Start a conversation

Mobility intelligence

The Spanish car market, measured from the dealership visit

20 brands and 2,085 dealerships, over 92 days and under one single qualified visit. No anchor brand and no surveys: only the physical visit that already happened.

Read the report

Read it in full online, no sign-up. To take the PDF with you we ask for your email.

The seven cuts

Seven questions that get answered in a budget meeting, not a marketing one: who gets the visit, with what network, from which public and from where.

01

Renault and Dacia lead, but they are almost the same public

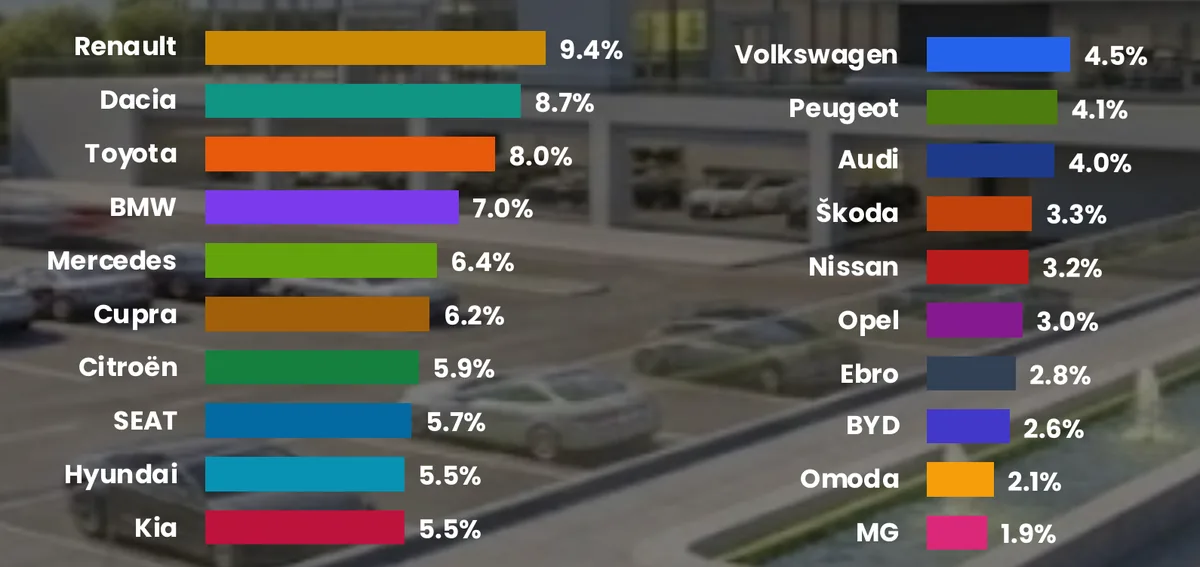
On devices per point of sale added up, Renault holds 9.4 % of the combined market, Dacia 8.7 % and Toyota 8.0 %; but Renault and Dacia share almost all of their public, and counted by devices per brand, Toyota (4,715) comes out above Renault (4,678). Among the premium brands, BMW (7.0 %) and Mercedes (6.4 %) sit ahead of generalists such as Citroën (5.9 %), SEAT (5.7 %) or Hyundai (5.5 %). The Chinese brands close the table: BYD 2.6 %, Omoda 2.1 % and MG 1.9 %. This is dealership traffic, not sales.
02

Efficiency per dealership draws a different ranking

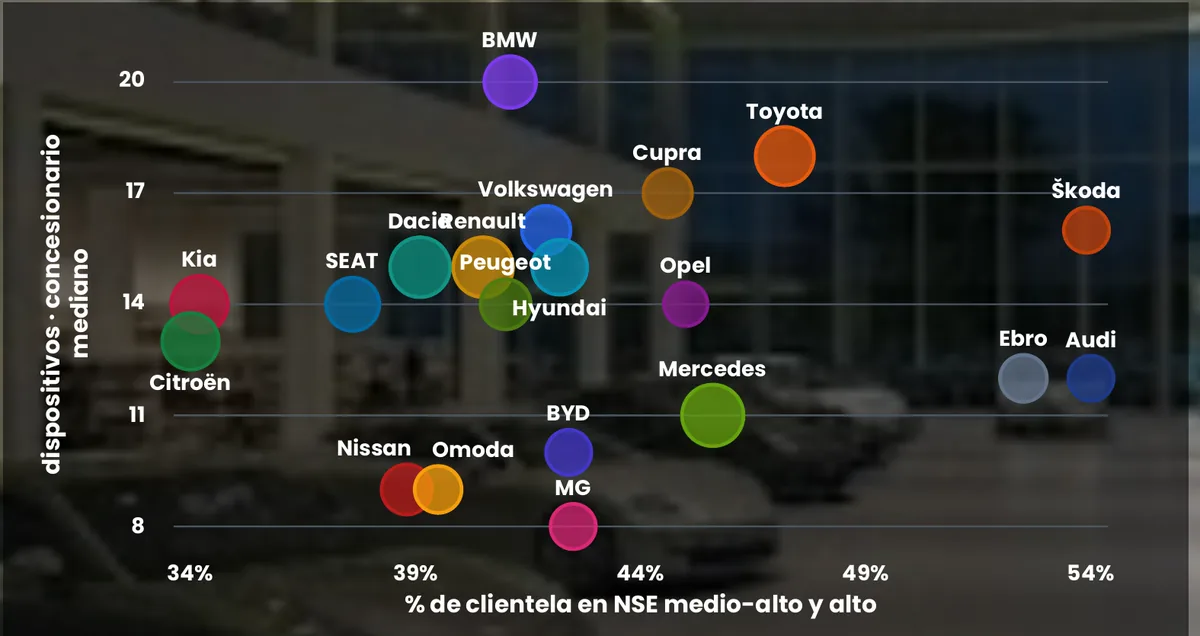
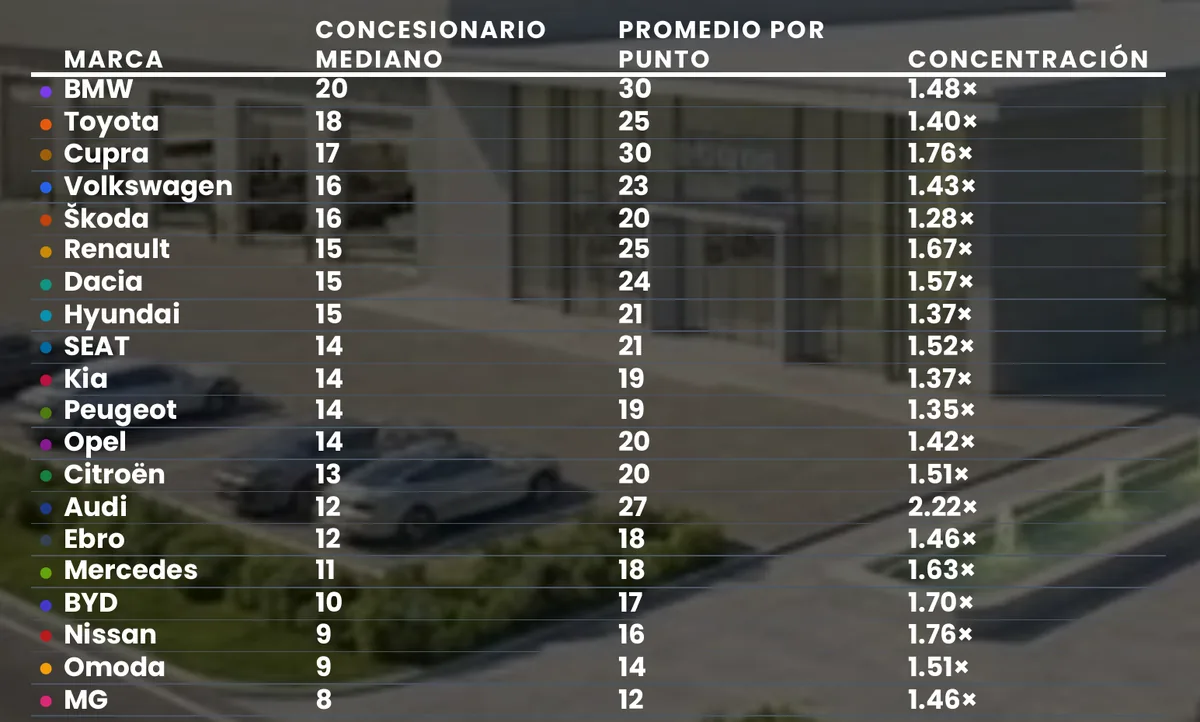
The median BMW dealership receives 20 devices in the quarter, Toyota’s 18 and Cupra’s 17 with a network of just 89 points. Škoda has the most even network (concentration of 1.28×) and Audi the most uneven: 27 devices per point on average, but 12 at the median (2.22×). Mercedes, with 162 dealerships, stays at 11; Nissan, Omoda and MG, between 8 and 9.

03

Who walks into each dealership, by socioeconomic level

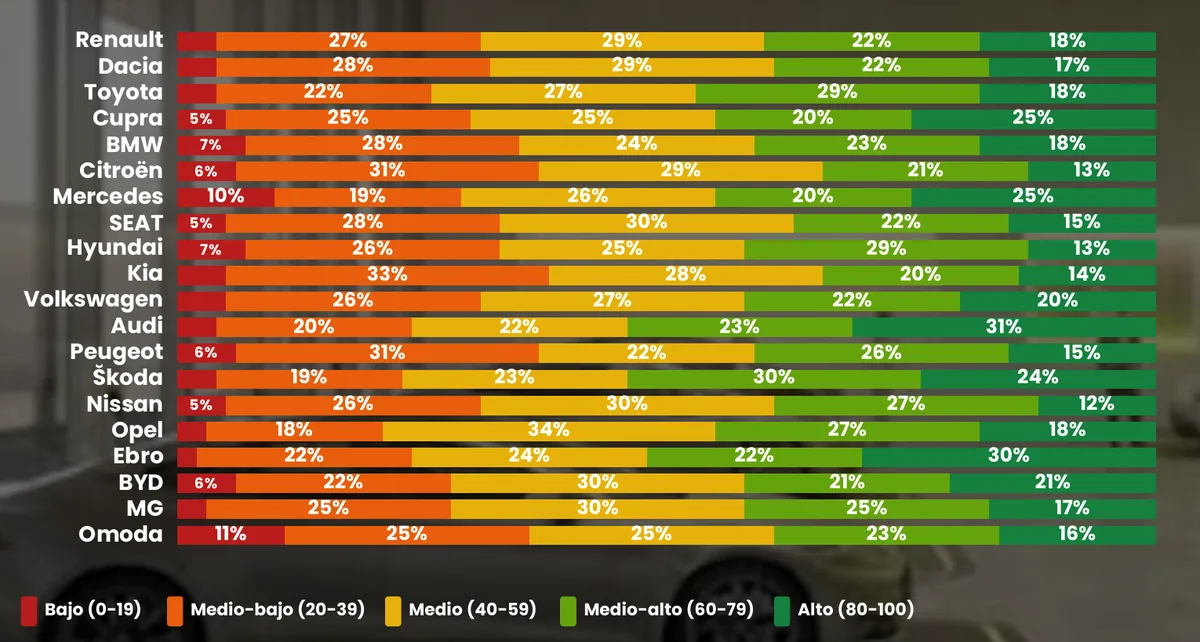
Audi is the brand with the most high-level visitors (31 %), and Mercedes and Cupra also carry real weight in that segment (25 % each); Mercedes also draws a polarised public, with 10 % at the low level. At the other end, Nissan (12 %), Citroën (13 %) and Hyundai (13 %) have the smallest high-level presence, and Omoda receives the most low-level visitors (11 %). The high-level bars are a floor, not a central estimate: the panel under-represents affluent customers.

04

Purchasing power against traffic

Toyota and Cupra hold the most favourable position: 18 and 17 devices at the median dealership, with an upper-middle public. BMW is the brand with the most traffic per point (20), but with visitors of an intermediate profile; Audi and Mercedes draw a high-level public with less traffic per dealership (12 and 11). Kia and Citroën keep acceptable traffic with the lowest profile, and Nissan, Omoda, BYD and MG combine low traffic and a moderate profile.

05

Which brands share the visitor

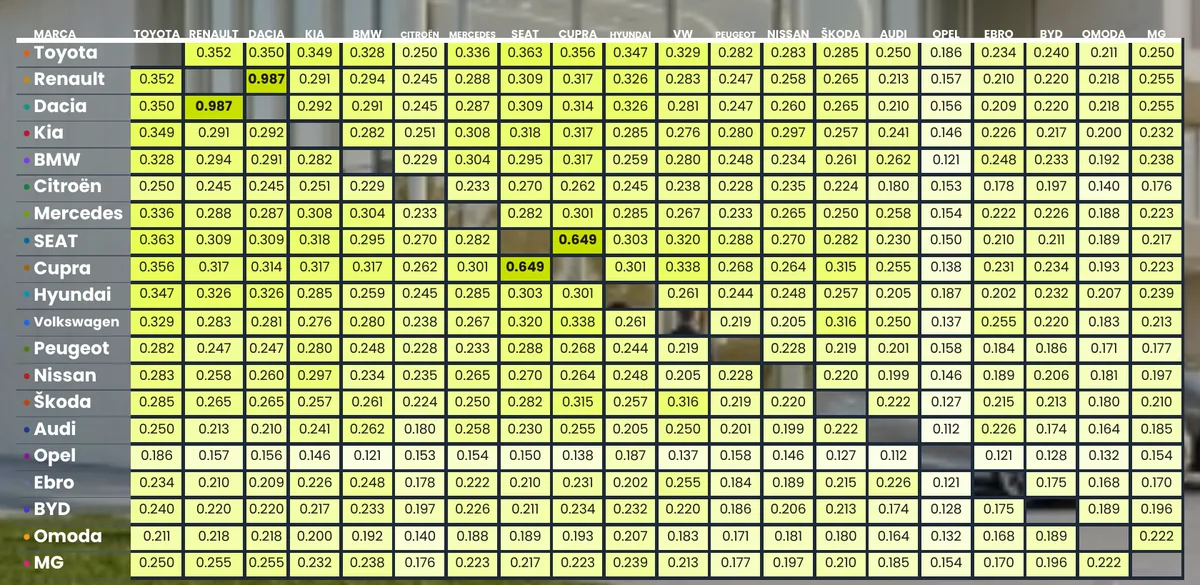
Renault and Dacia are practically the same audience (similarity of 0.987 out of 1), a reflection of their shared network, and SEAT and Cupra also overlap heavily (0.649). Toyota is the most transversal brand: it shares its public with SEAT (0.363), Cupra (0.356) and Renault (0.352). Volkswagen and Škoda show the affinity of a shared group (0.316); Opel is the most isolated brand, with 0.187 at most, and the Chinese brands still have little public in common with the rest.

06

Where they come from

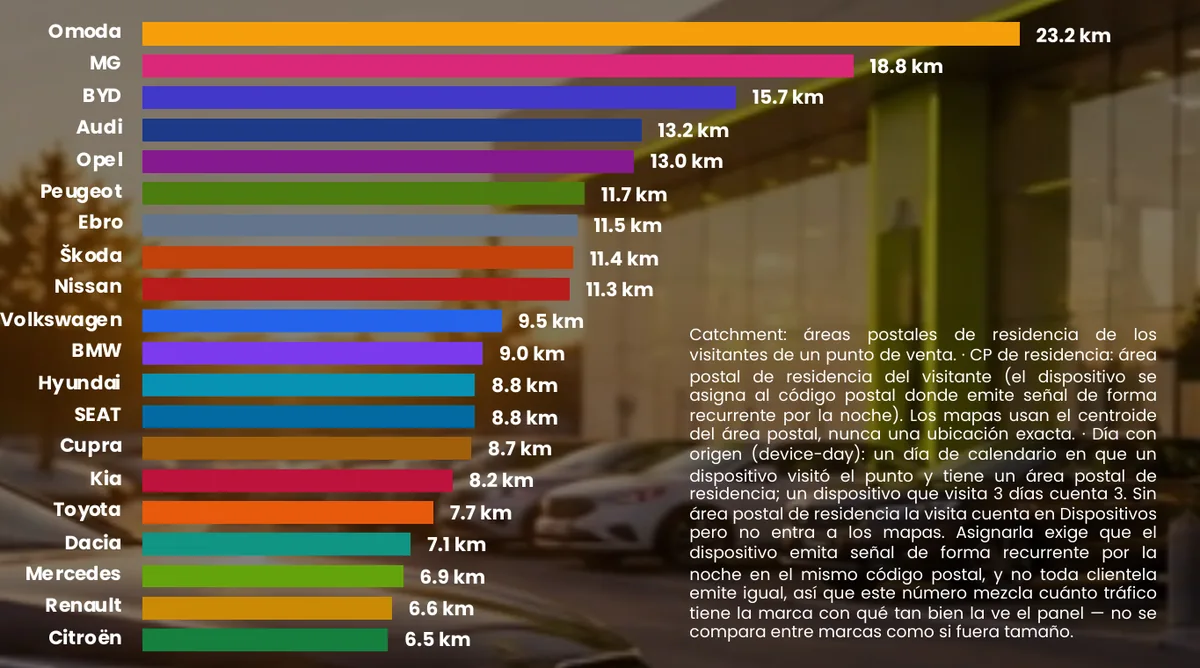
The Chinese brands draw the most distant visitor: 9 in 10 Omoda visitors live within 23.2 km of the dealership, against 18.8 km at MG and 15.7 km at BYD; their networks, still small, force people to travel. Citroën (6.5 km), Renault (6.6 km), Mercedes (6.9 km) and Dacia (7.1 km) capture the most local public, typical of dense networks. Ebro stands out for another reason: it is the brand with the largest share of visitors from more than 5 km away (33.8 %), against 13.5 % at Citroën.

07

Every region has its leader

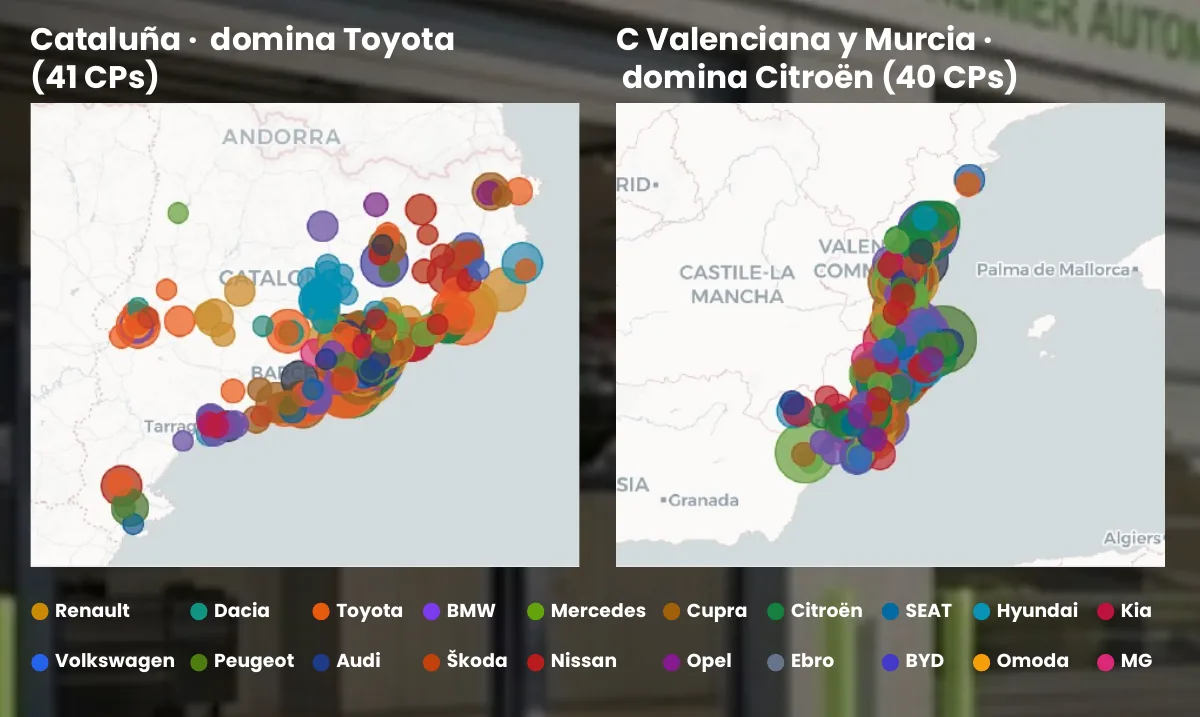
Renault dominates all four quadrants of Madrid, but outside the capital the map changes: in Catalonia Toyota leads (41 postcodes) with Cupra a step behind (38), and in Valencia and Murcia, Citroën (40) with BMW second (35), ahead of every other generalist. In Andalusia Kia (28) leads by the narrowest margin, with Peugeot (27) practically tied; in the North, Opel leads in 27 postcodes, almost double Audi (14); in Galicia Citroën and Hyundai tie (12) and in the Canaries Nissan leads (12).

Twenty brands, one criterion: the visit that already happened

Read the report