01
Market share
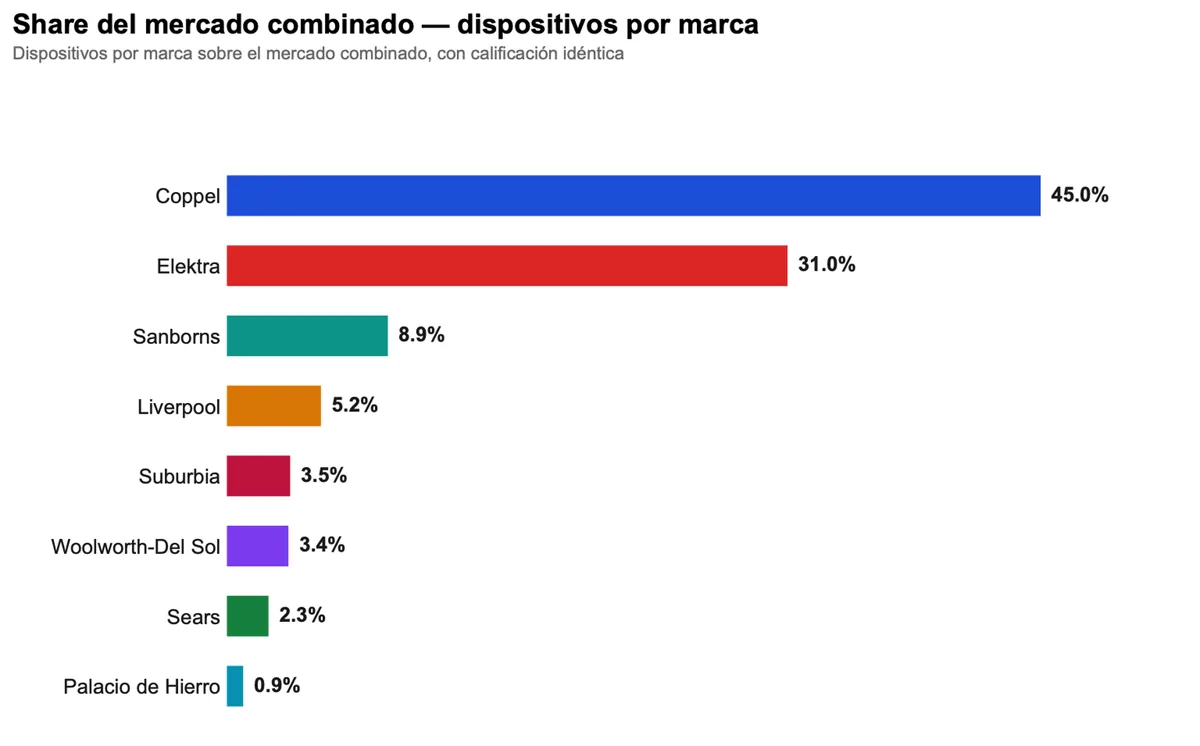
Coppel (45%) and Elektra (31%) together hold 76% of all measured traffic. El Palacio de Hierro, at 0.9%, tells the story of scale, not of value per customer.
Mobility intelligence
2.7 million devices, 8 brands and 3,777 stores from June to August 2026, under one single qualification. No anchor brand and no surveys: only the physical visit that already happened.
Read it in full online, no sign-up. To take the PDF with you we ask for your email.
Seven questions that get answered in a budget meeting, not a marketing one.
Coppel (45%) and Elektra (31%) together hold 76% of all measured traffic. El Palacio de Hierro, at 0.9%, tells the story of scale, not of value per customer.
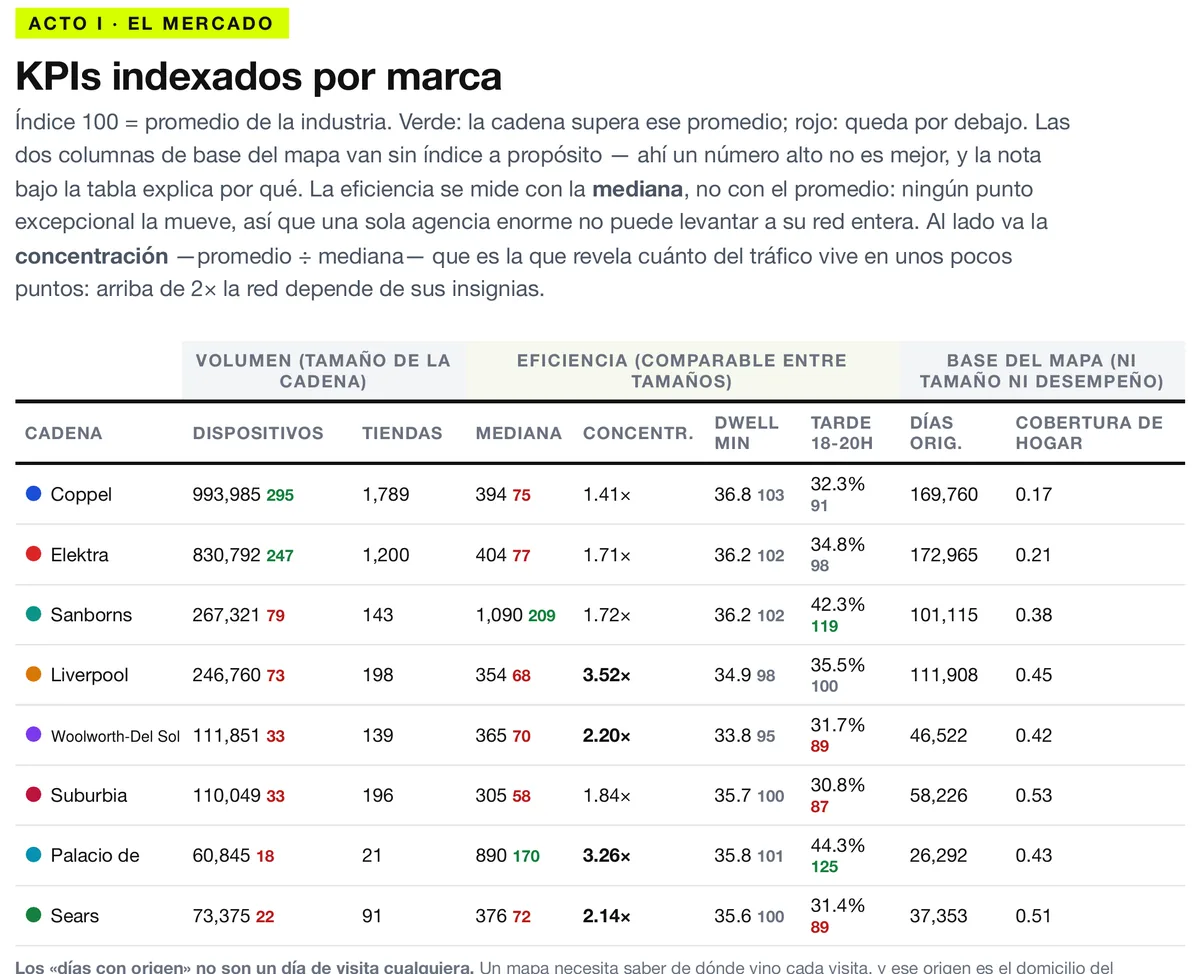
Volume and efficiency come apart: the largest networks are not the most efficient per point of sale. Sanborns has the highest traffic intensity per store.
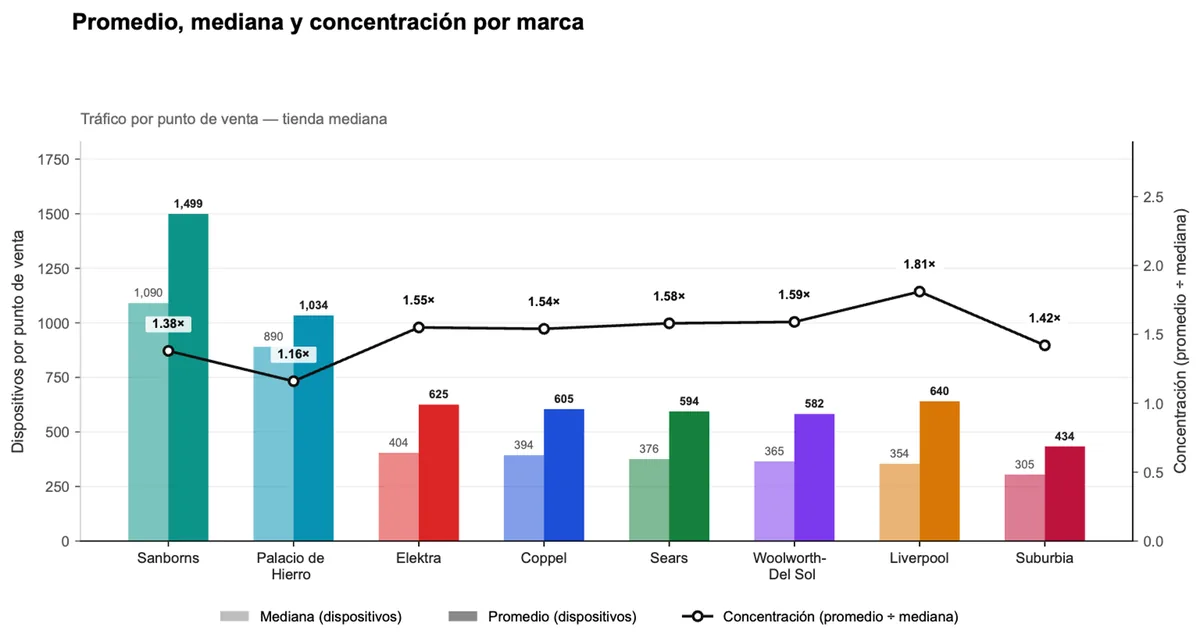
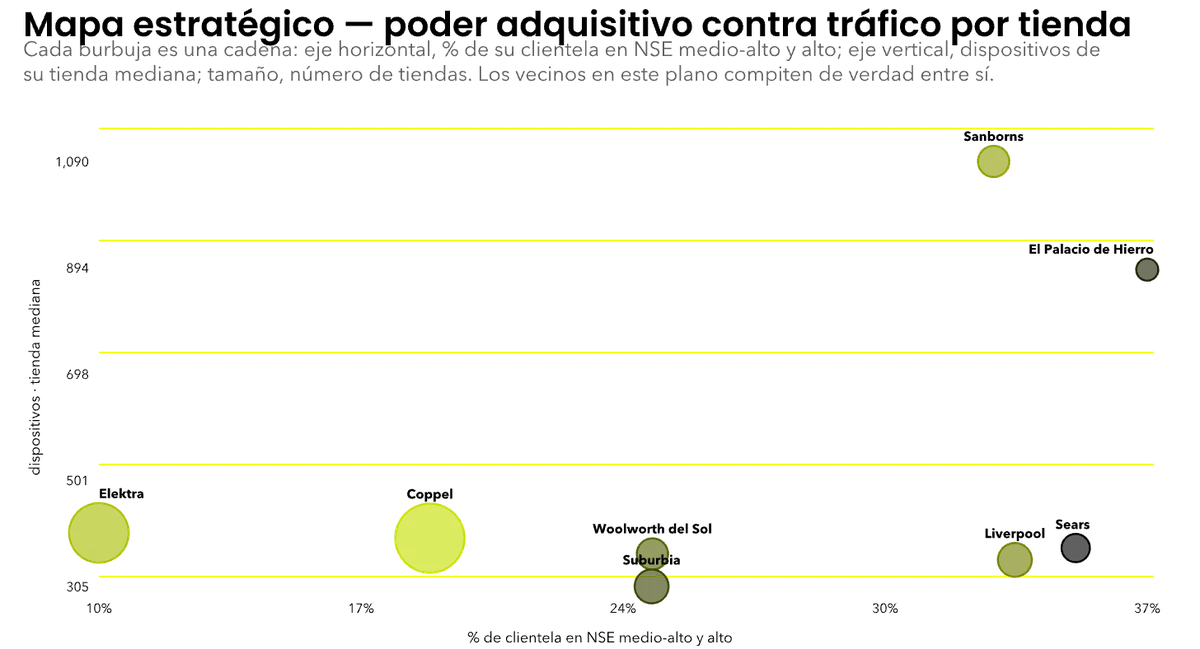
Sanborns and El Palacio de Hierro play in a different league per point of sale. Liverpool shows the highest concentration (1.81×): its result depends on a small group of stores.
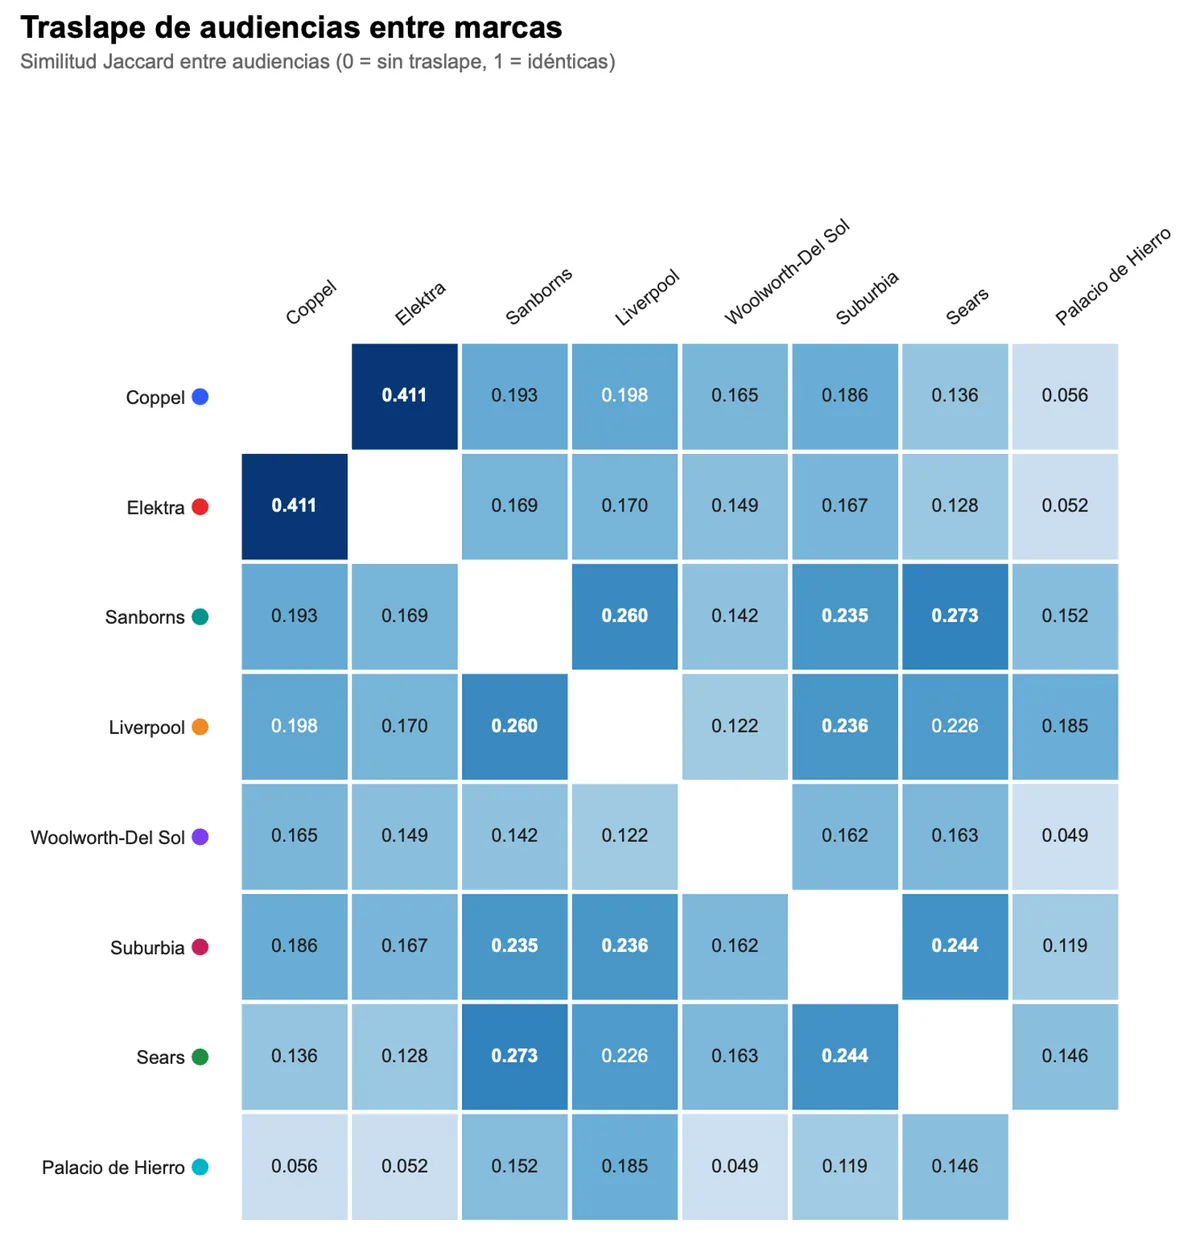
Coppel and Elektra share the same shopper and their audiences are largely interchangeable. El Palacio de Hierro is the brand with the least overlap with the rest.
Purchasing power against traffic per store: Sanborns and El Palacio de Hierro sit in the highest-value quadrant; Coppel and Elektra compete on reach, not on ticket.
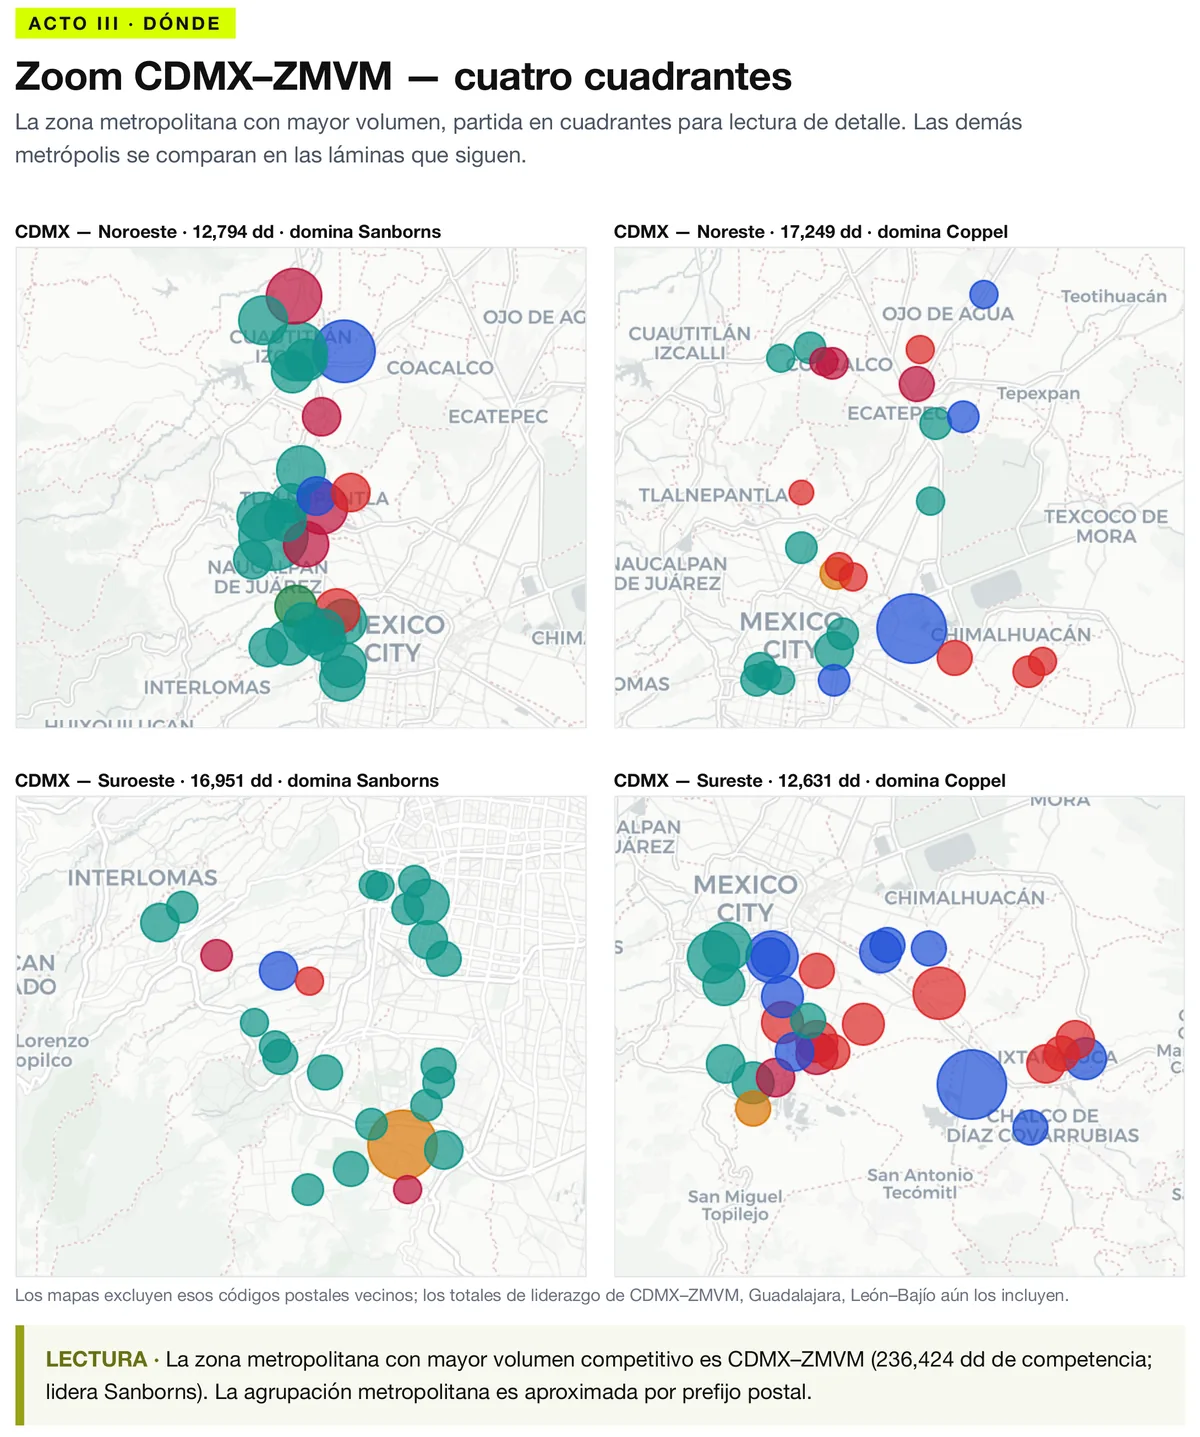
Leadership splits by quadrant: Sanborns rules the west (Naucalpan, Interlomas) and Coppel the east (Ecatepec, Chimalhuacán, Ixtapaluca).
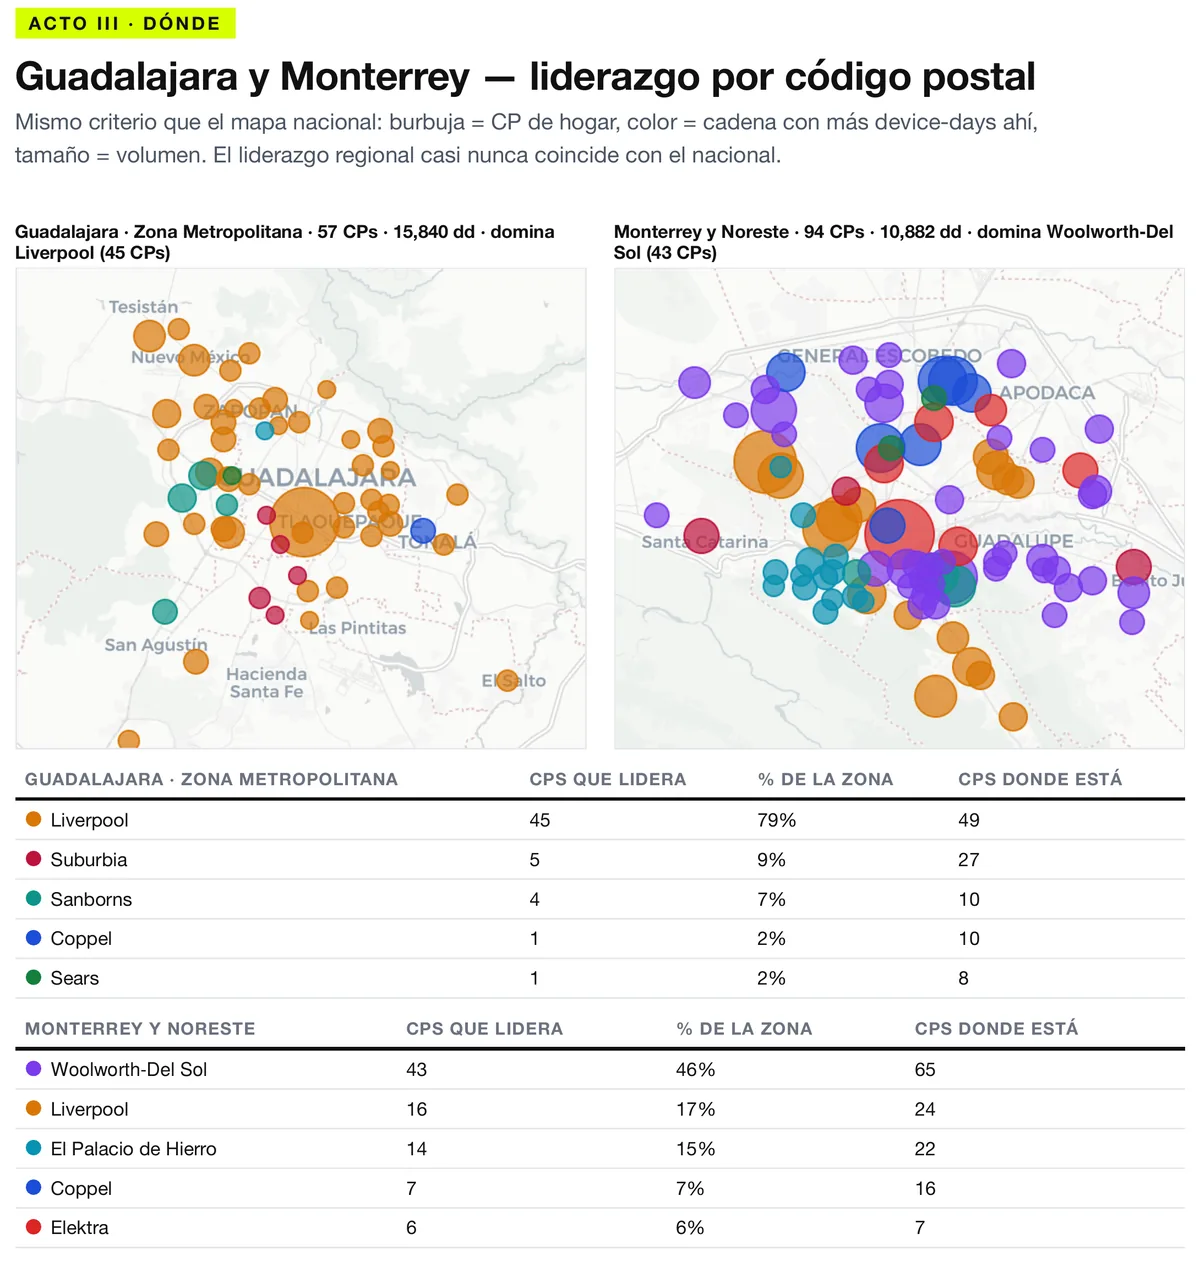
Guadalajara belongs to Liverpool almost unchallenged; Monterrey is a fragmented market where Woolworth-Del Sol leads among five brands. El Bajío is the most contested region in the country.