Start a conversation

Mobility intelligence

Home and decor retail in Spain, measured from the store visit

Eight chains and 367 furniture and decor stores, measured under one rule across the 30 days of September 2026. No anchor brand and no surveys: only the physical visit that already happened.

Read the report

Read it in full online, no sign-up. To take the PDF with you we ask for your email.

The seven cuts

Seven questions that decide assortment, location and media budget, not a campaign.

01

Two chains, six in ten

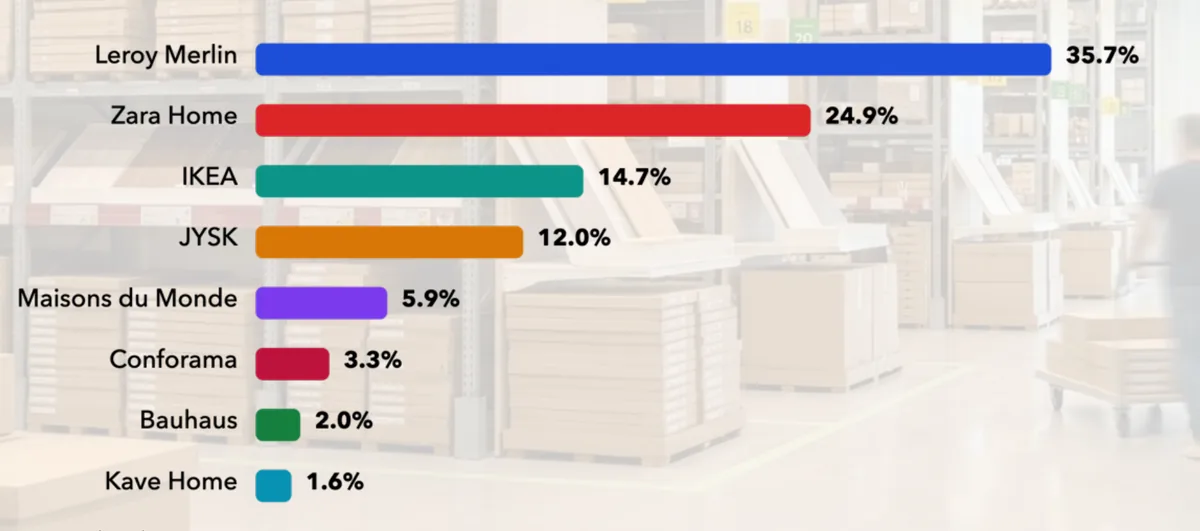
Leroy Merlin gathers 35.7 % of devices by brand, summed, and Zara Home 24.9 %: six in ten between the two. IKEA (14.7 %) and JYSK (12.0 %) complete the large block; Maisons du Monde, Conforama, Bauhaus and Kave Home add up to 12.8 % between the four.
02

Volume is not efficiency

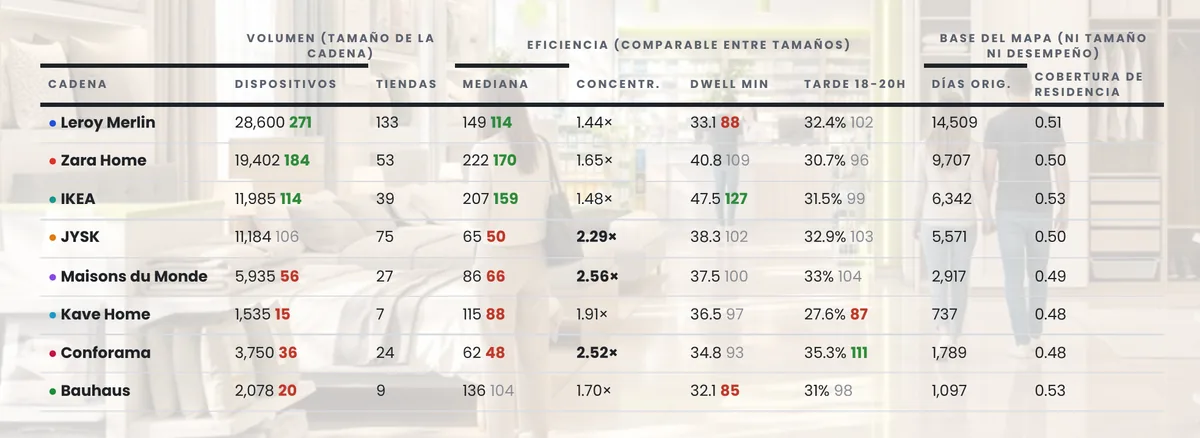
Leroy Merlin, with 133 stores and 28,600 devices, has a median store of 149 devices and a short visit: 33.1 minutes. Zara Home and IKEA lead per store, 222 and 207, and IKEA keeps people longer: 47.5 minutes. JYSK spreads 75 stores at a median of 65; Maisons du Monde and Conforama are the most concentrated networks, 2.56× and 2.52×, and Conforama the most evening-heavy: 35.3 % of its visits between 18:00 and 20:00.

03

Traffic without the location effect

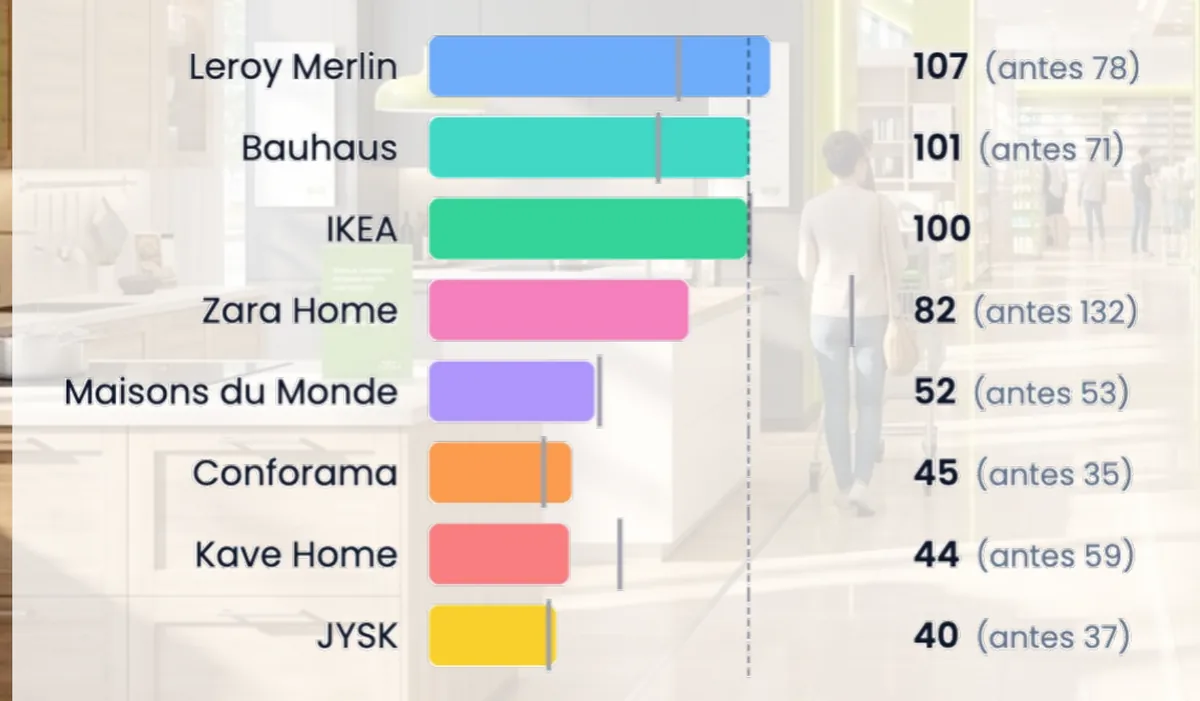
Discounting how many shops surround each store and whether it sits inside a mall, Zara Home drops from 132 to 82 on an IKEA = 100 base: a good part of its traffic comes from the site, not the brand. Leroy Merlin rises from 78 to 107 and Bauhaus from 71 to 101: they draw more than their location explains.

04

Volume and value come apart

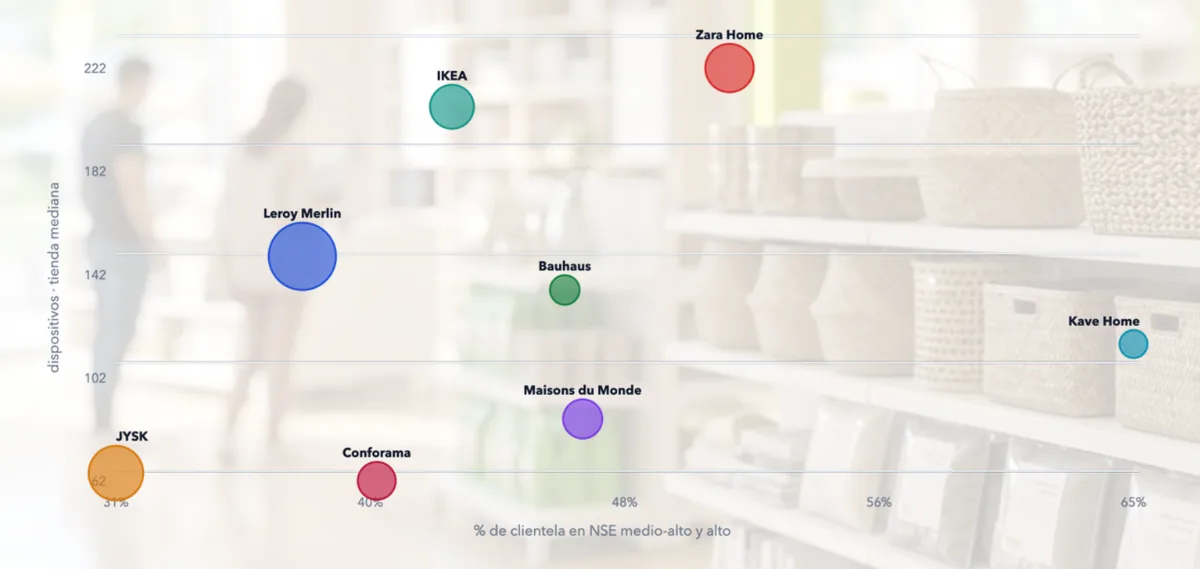
Kave Home has the highest profile: 65 % of its visitors in upper-middle and high socioeconomic bands. JYSK the lowest, 31 %, and Leroy Merlin, the traffic leader, 37 %. Zara Home has both: 222 devices per median store and 28 % of its clientele in the top band. Bottom left of the map, JYSK and Conforama share the lowest traffic per store, 65 and 62, and the least affluent clientele: they compete on price.

05

Who shares visitors with whom

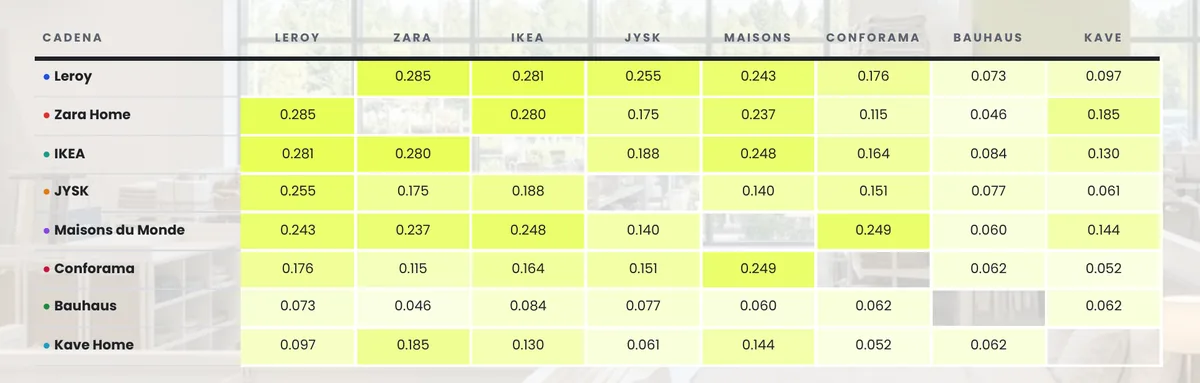
Leroy Merlin, Zara Home and IKEA form the triangle that shares the most visitors: Jaccard of 0.285, 0.281 and 0.280. Maisons du Monde acts as a bridge and its natural pair is Conforama (0.249); Kave Home pairs with Zara Home (0.185). Bauhaus stands alone: its highest overlap is 0.084, with IKEA.

06

Where they come from

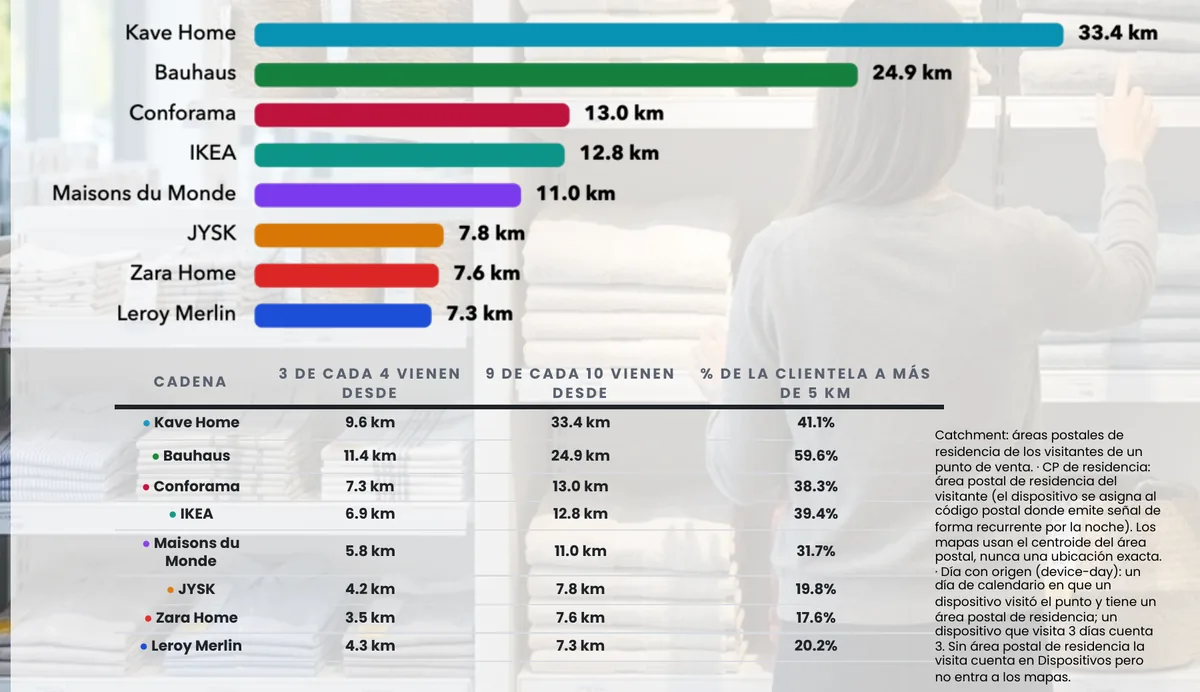
Kave Home and Bauhaus are destinations: 9 in 10 visitors live within 33.4 and 24.9 km, and 41.1 % and 59.6 % more than 5 km away. Zara Home, Leroy Merlin and JYSK are proximity: 3 in 4 live within 3.5, 4.3 and 4.2 km, and only 17.6 %, 20.2 % and 19.8 % beyond 5. IKEA sits in between, 12.8 km for 9 in 10: it competes across the whole metropolitan area, not just near each store.

07

Leadership by postcode

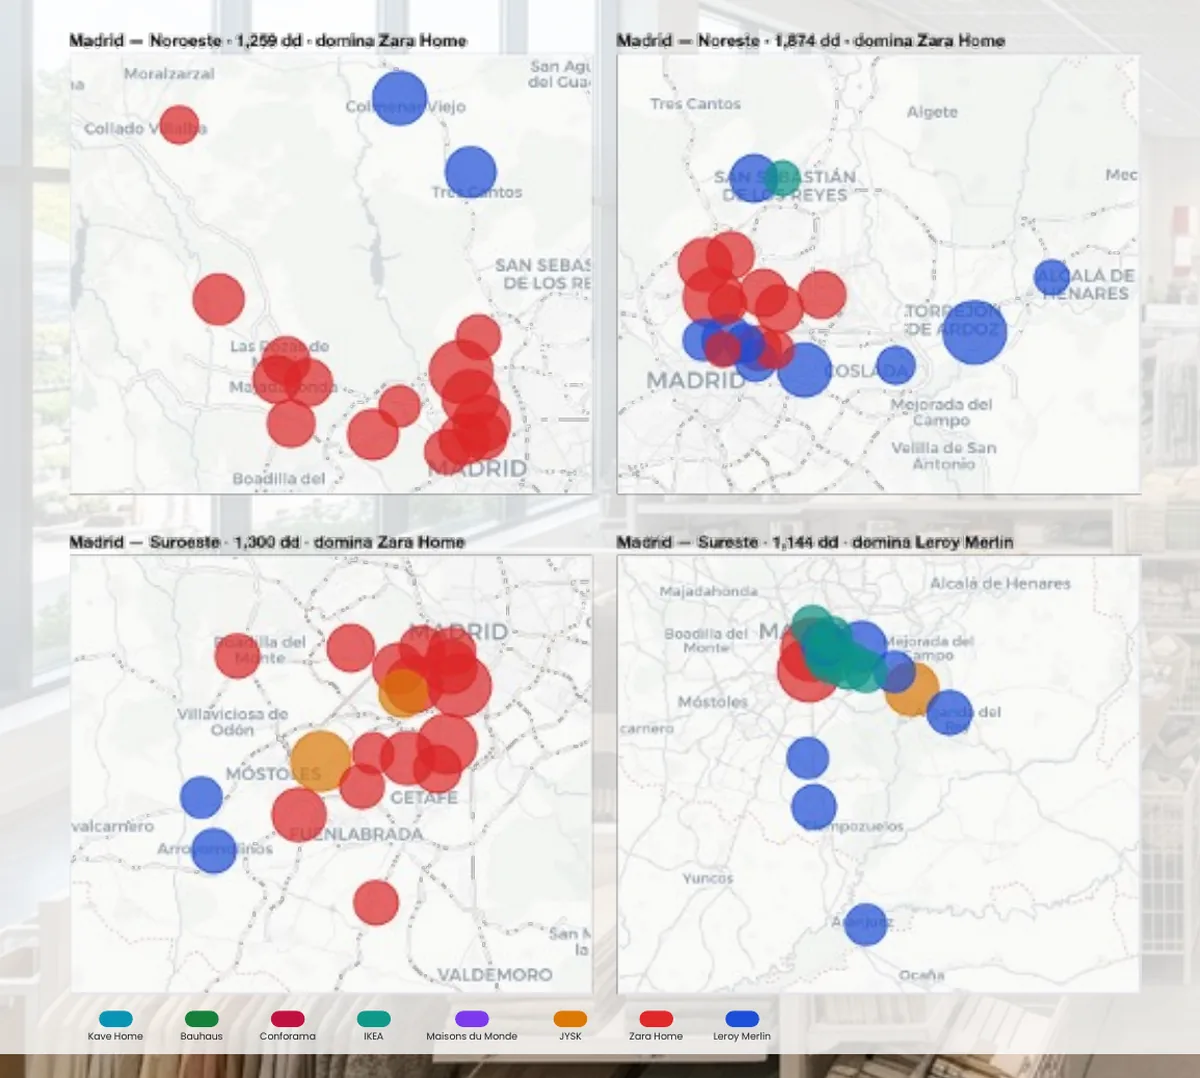
Madrid is the most contested market and Zara Home dominates three of the four quadrants. Outside Madrid, Leroy Merlin rules: in Catalonia it wins 35 of the 40 postcodes where it is present (44 % of the zone), 59 in the Valencian Community and Murcia (48 %) and 27 of 36 in the North. Andalusia is split: Zara Home leads 30 postcodes and Leroy Merlin 27. Only postcodes with at least 10 visit days count.

More footfall does not mean a bigger basket

Read the report